Simmons First National Beat Consensus Estimates
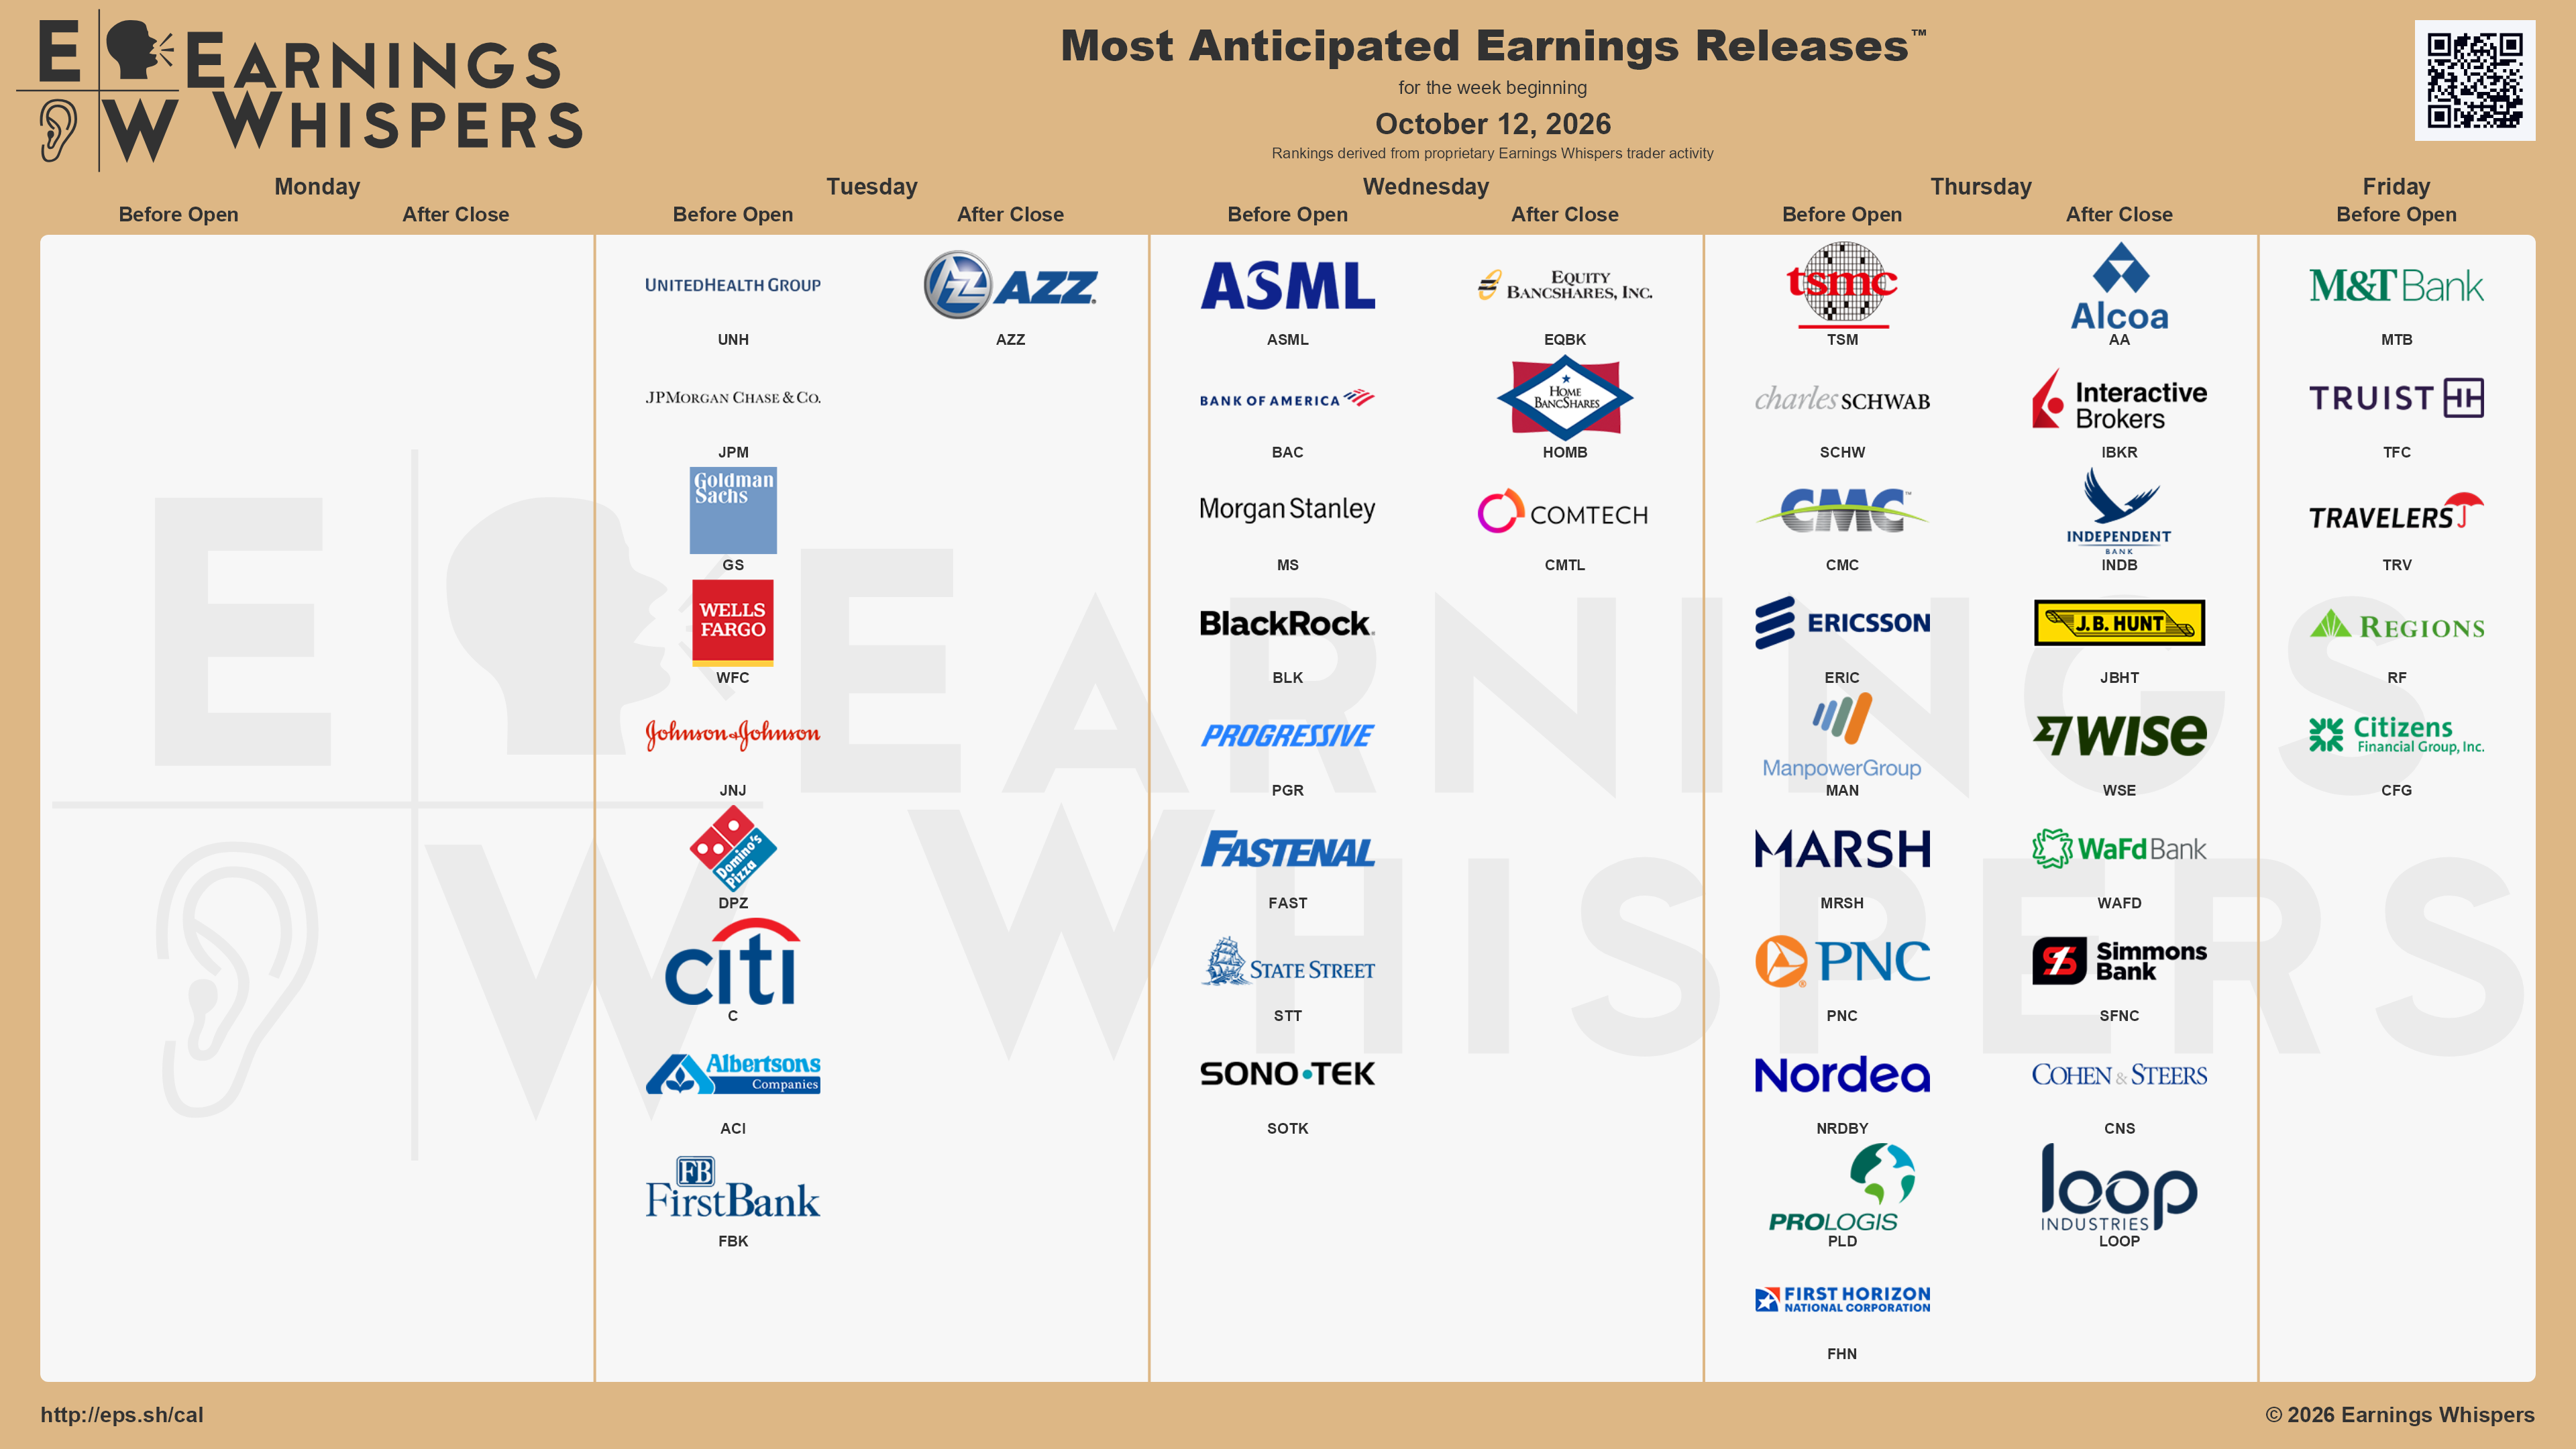
Thursday, October 15, 2026 at 4:30 PM
Simmons First National (SFNC) reported earnings of $0.54 per share on revenue of $356.23 million for the third quarter ended September 2026. The consensus earnings estimate was $0.53 per share on revenue of $255.21 million. The company beat consensus estimates by 1.89% while revenue fell 0.42% compared to the same quarter a year ago.
Simmons First National Corp is a financial holding company. The Company through its subsidiaries is engaged in providing banking services including home loan, investment banking, and personal banking services to individual and corporate customers.
Simmons First National Corp is a financial holding company. The Company through its subsidiaries is engaged in providing banking services including home loan, investment banking, and personal banking services to individual and corporate customers.